Retirees taking required minimum distributions (RMDs) face a familiar problem. Every year the Internal Revenue Service (IRS) forces money out of the individual retirement account (IRA) whether or not markets cooperate, and every year inflation erodes what that money buys. Treasury Inflation-Protected Securities (TIPS) address both, and an IRA is the best place to hold them.
How TIPS work. TIPS principal rises with the Consumer Price Index (CPI). The coupon rate is fixed but paid on the adjusted principal, so income grows with prices. At maturity you receive the adjusted principal or original face value, whichever is higher. Backed by the US government, TIPS lock in a real yield: a guaranteed return above inflation.
Today's opportunity. A September reopening of the 10-year TIPS cleared at a 2.653% real yield, the best result for that term since October 2008. Breakevens sit near 2.37% at 5 years and 2.36% at 10, below the 3.4% average inflation of the past decade.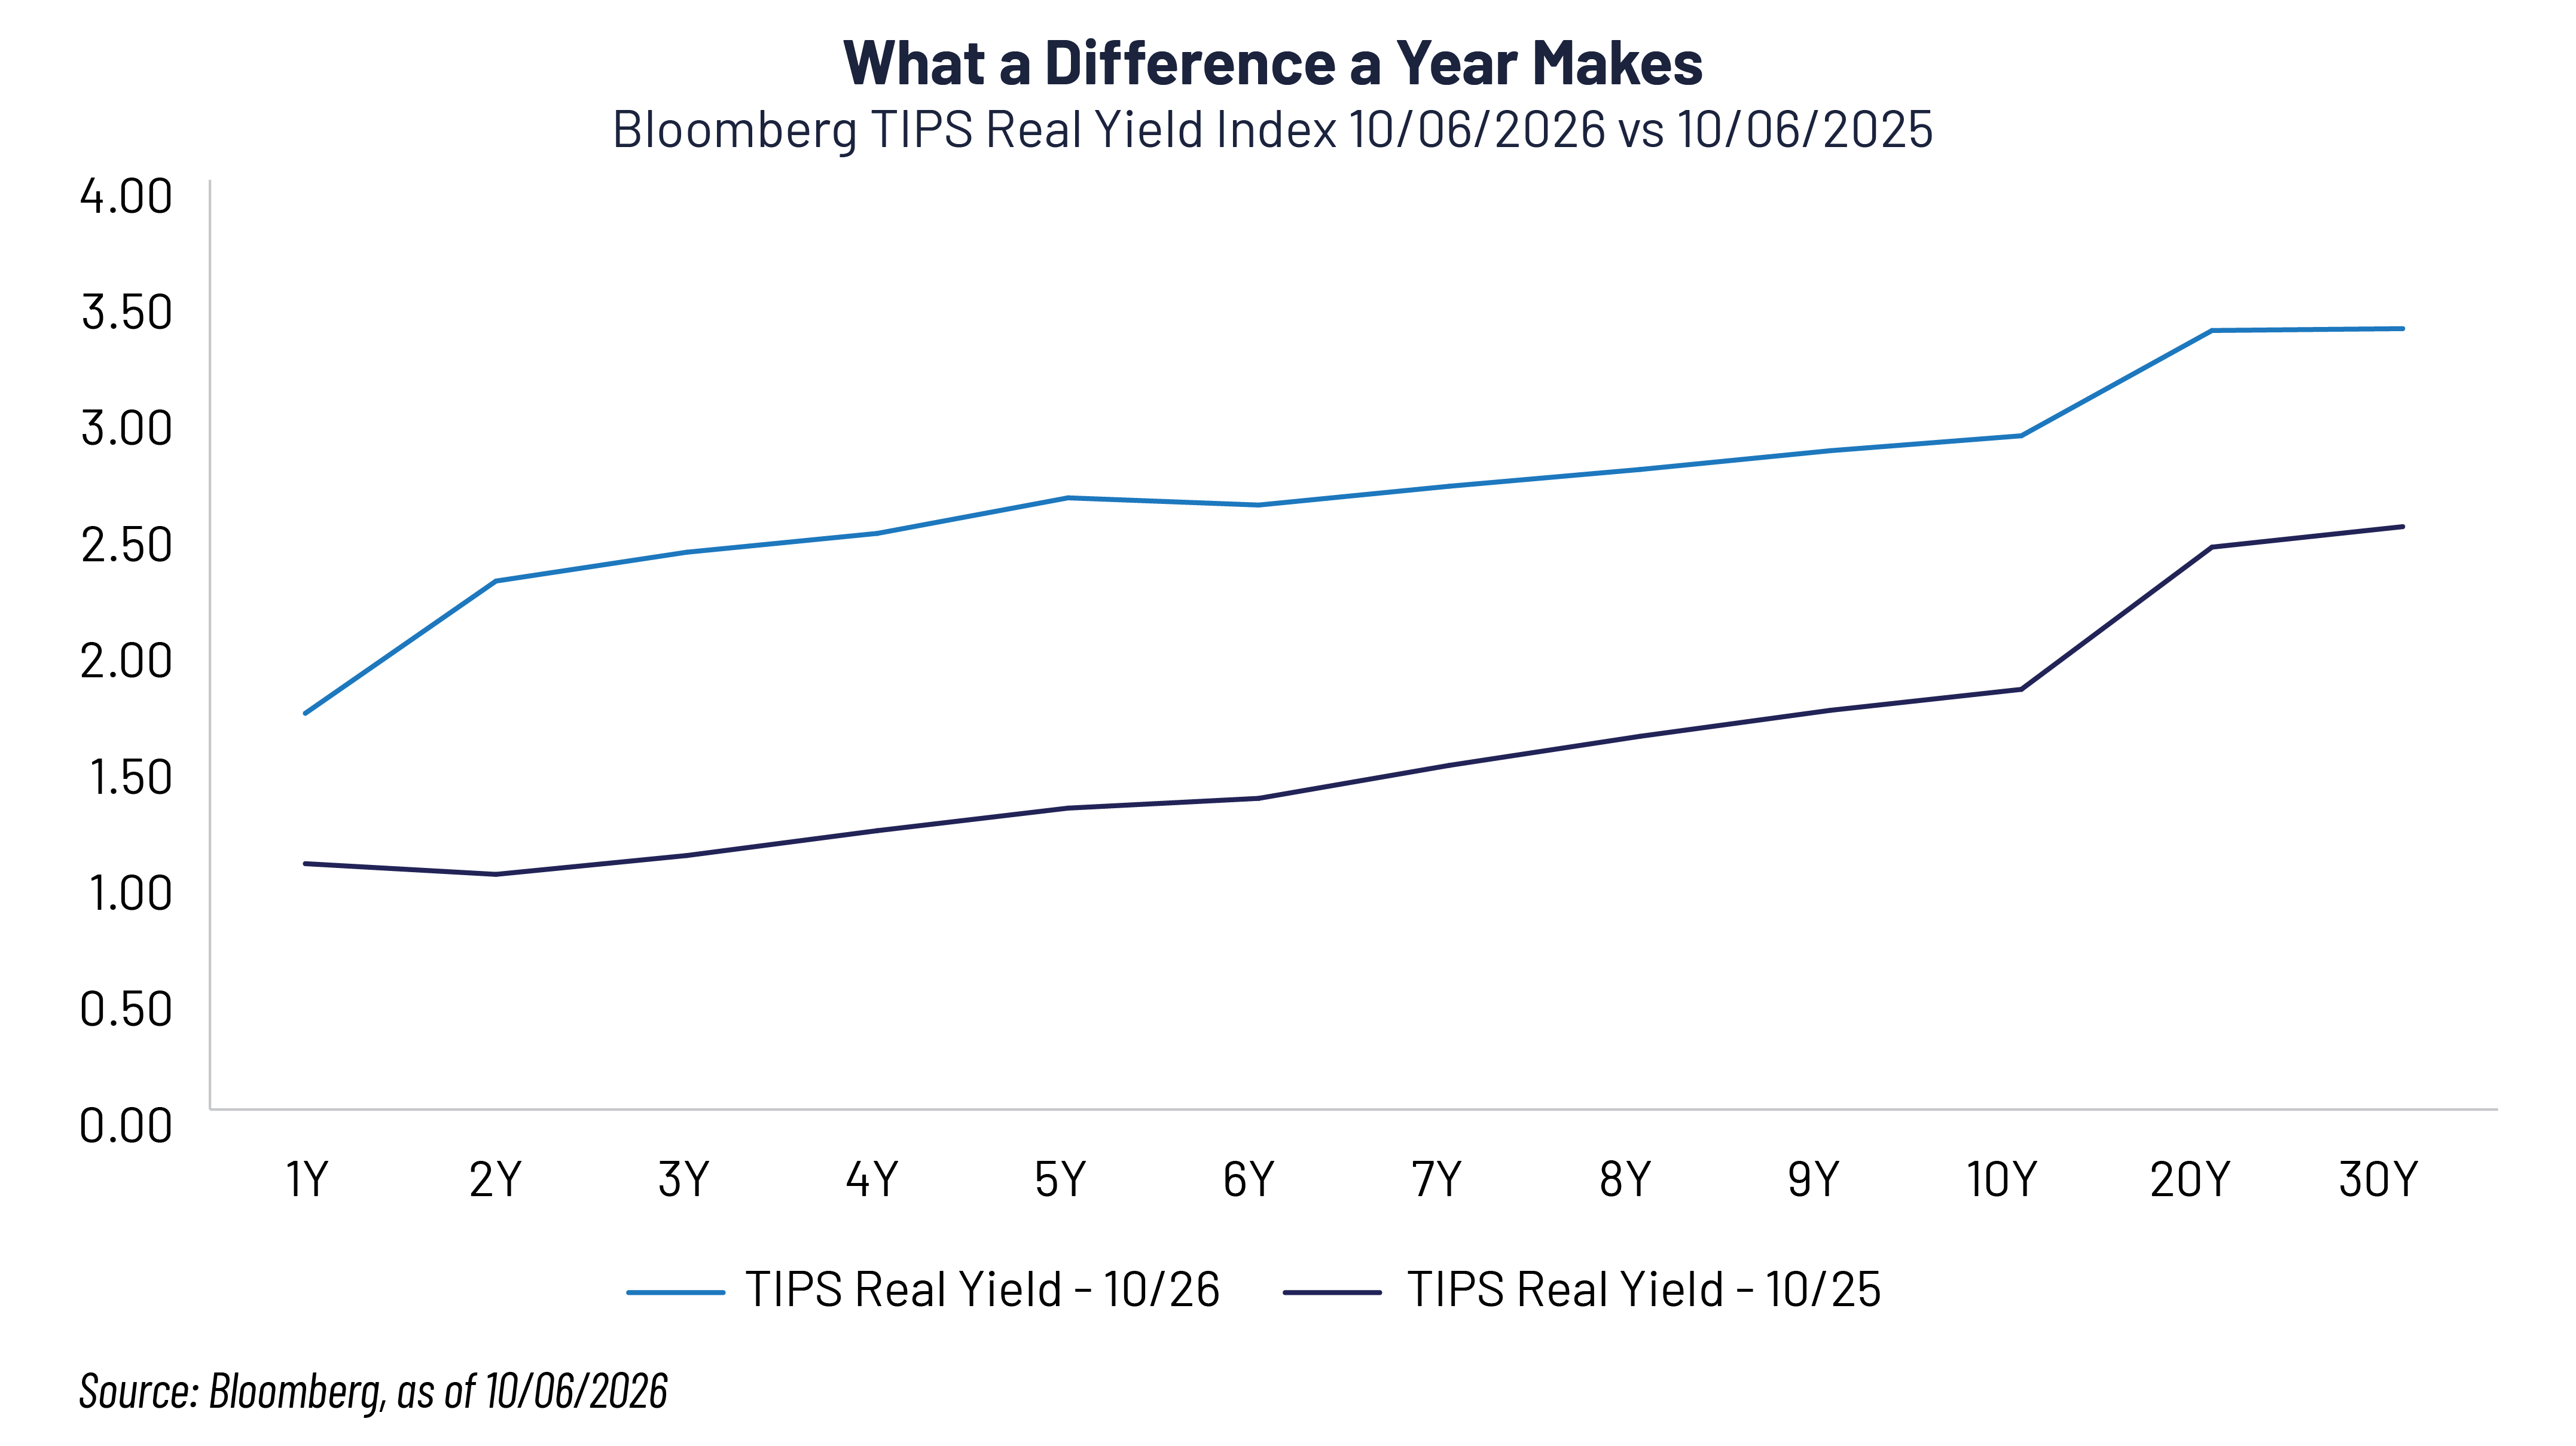 Why the IRA matters. In a taxable account, each year's inflation adjustment is taxed as "phantom income" before you receive it. Inside an IRA, that drag disappears.
Why a ladder fits RMDs. A ladder holds bonds maturing in consecutive years, sized to each year's expected distribution. Maturing rungs fund the RMD, so you never sell stocks after a crash or bonds after a rate spike to meet a mandatory withdrawal.
Need more income? Nominal Treasuries can be mixed in. On September 25, the 10-year nominal yielded 5.17%, well above its TIPS counterpart's real yield. One approach is nominals for the early rungs, where inflation has less time to compound, and TIPS for later years. Remember too, that spending each maturing rung's principal, not just its coupons, is the biggest income lever. Every nominal rung though, reintroduces inflation risk: if inflation tops the roughly 2.4% breakeven, that extra early income costs you later.
Other things to consider. A TIPS ladder isn't right for everyone:
-
You don't need the money. If RMDs get reinvested or the IRA is meant for heirs, a long-horizon equity allocation or exposure to real assets may likely grow more.
-
RMDs are a moving target. They're based on the total IRA balance, so ladder rungs are estimates and won't match exactly.
-
Selling early hurts. TIPS prices fall when real yields rise; the guarantee only holds to maturity. Remember, TIPS are just Treasury securities, subject to losing value just like regular nominal Treasuries unless held to maturity.
-
CPI isn't your inflation. Retirees' costs, especially healthcare, can outpace the index.
- Time horizons don’t match. TIPS ladders make more sense in the belly of the curve, currently three to seven years, where breakevens versus nominals are lowest. You may want to consider nominal treasuries, or a high-quality short duration model for the first couple years of cash flow needs, even though not inflation adjusted.
The free lunch. Investors usually pay for insurance. With breakevens near 2.4%, inflation protection is cheap, and a near-3% real yield, tax shelter and cash matched to known obligations make it about as close to a free lunch as fixed income gets, for retirees who value certainty over upside.
Important Disclosures & Definitions

AAI001252